

Articles
WHY CHINA IS BUYING MORE GOLD BUT LESS JEWELRY
Gold purchases in China are nearly level with a year ago, but demand for jewelry and investment bullion is diverging. What is shifting in consumer choices—and why are retailers rethinking how they measure profit?
What Happened Over the Half-Year
The China Gold Association (CGA) report, published on 6 August 2026, presents figures for January–June. Total consumption rose by just 1.2% to 511.4 tonnes. Behind this virtually unchanged total lie two opposing trends.
| Category | H1 2026, tonnes | vs. H1 2025 |
|---|---|---|
| Jewelry | 132.1 | −33.9% |
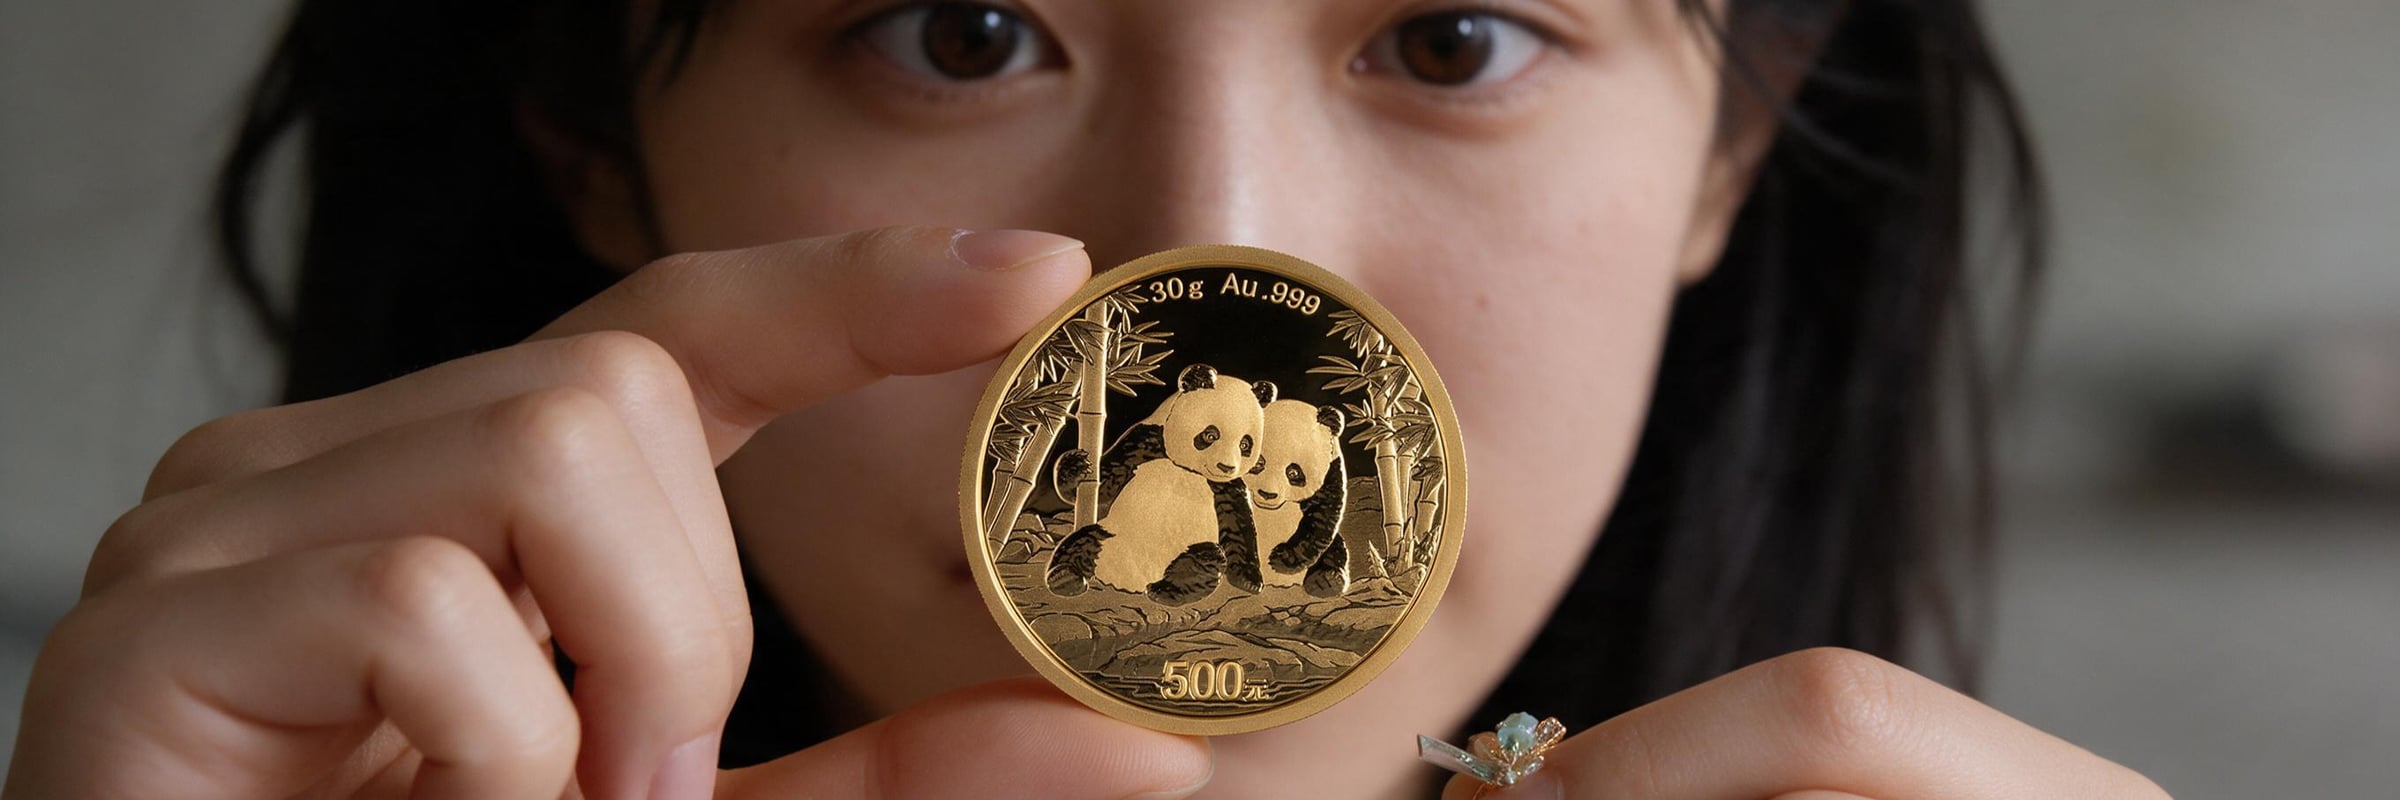
| Bars and coins combined | 339.3 | +28.4% |
According to editorial calculations based on the complete CGA statistics, bars and coins accounted for about two-thirds of consumption: 339.336 tonnes out of 511.412. The association attributes the divergence between categories to high and volatile prices, as well as a new tax policy. Periods of falling prices supported bullion sales through banks.
However, such a breakdown does not track individual consumer actions. It does not prove that a previous ring buyer necessarily opted for a gold bar, or that the population closed bank deposits en masse. The statistics show changes in the relative weight of product categories rather than the individual journey of each customer.
Buying Jewelry vs. Buying Bullion
These purchases serve different purposes. Jewelry is chosen for wear, gifts, or weddings—where both weight and appearance matter. In an investment product, the physical metal itself takes center stage. This distinction helps explain how aggregate demand can stay virtually flat while sales across individual categories diverge so sharply.
The price per gram does not answer every question either. When comparing finished pieces, buyers must distinguish between the cost of the gold content and the price of the finished item itself. That ratio varies by specific product; a national demand report cannot quantify the premium on each individual piece of jewelry or coin.
There is another pitfall: tonnage and revenue measure different things. Tonnage sold reflects the quantity of metal. Monetary turnover also depends on the sales price. Therefore, a decline in the weight of jewelry sold does not, by itself, reveal how revenue and profits shifted for any given retailer.
Why Higher Sales Can Dilute Gross Margins
A report by Yicai from 9 September highlights a concrete example: Chow Tai Seng. The company informed investors that it expanded sales of investment bars in the second quarter. This business line generated heavy turnover at a low gross margin, which dragged down overall profitability across its online channel. The company urged observers to look more closely at absolute gross profit rather than solely at margin percentage.
This is a vital distinction. Profit margin percentage reflects the share of revenue remaining after cost of goods sold; absolute gross profit is the actual amount of money left over. If product mix shifts toward high-volume items with lower margin percentages, one metric can deteriorate without a corresponding decline in the other. A percentage alone cannot capture overall business performance.
Viewed through this lens, the Chinese market is particularly interesting for the shifting composition of purchases. The headline figure—"demand rose by 1.2%"—almost conceals what is truly taking place. To understand the shifts, one must look at categories, physical tonnage, and retailer economics: each metric answers a distinct question.